Present bias
resource library
Earlier, we assumed a single article could explain present bias and people would simply adjust their saving habits. Now, we know change needs concrete tools, repeatable prompts, and clear language. This resources library collects our most practical materials: checklists to slow down spending decisions, comparison tables that show how choices add up over years, and glossaries that translate behavioural finance into plain speech. Everything here is designed for busy lives in India and meant to be tested in small experiments, not treated as a promise of any particular result. Past performance does not guarantee future outcomes, and results may vary.
Key saving resources
Present bias decision checklist
Use this short checklist before major spending decisions to see where present bias might be nudging you toward today at the expense of future goals. It walks you through a few quick questions about timing, emotional state, and trade offs, then suggests small adjustments you can test over the next few weeks. Results may vary for each person.
Multi year saving path table
This template helps you compare different saving paths side by side over several years using rounded numbers. You can plug in your own figures to see how repeated choices during salary days, sales, and festivals might shift your long term picture, while remembering that past performance does not guarantee future results.
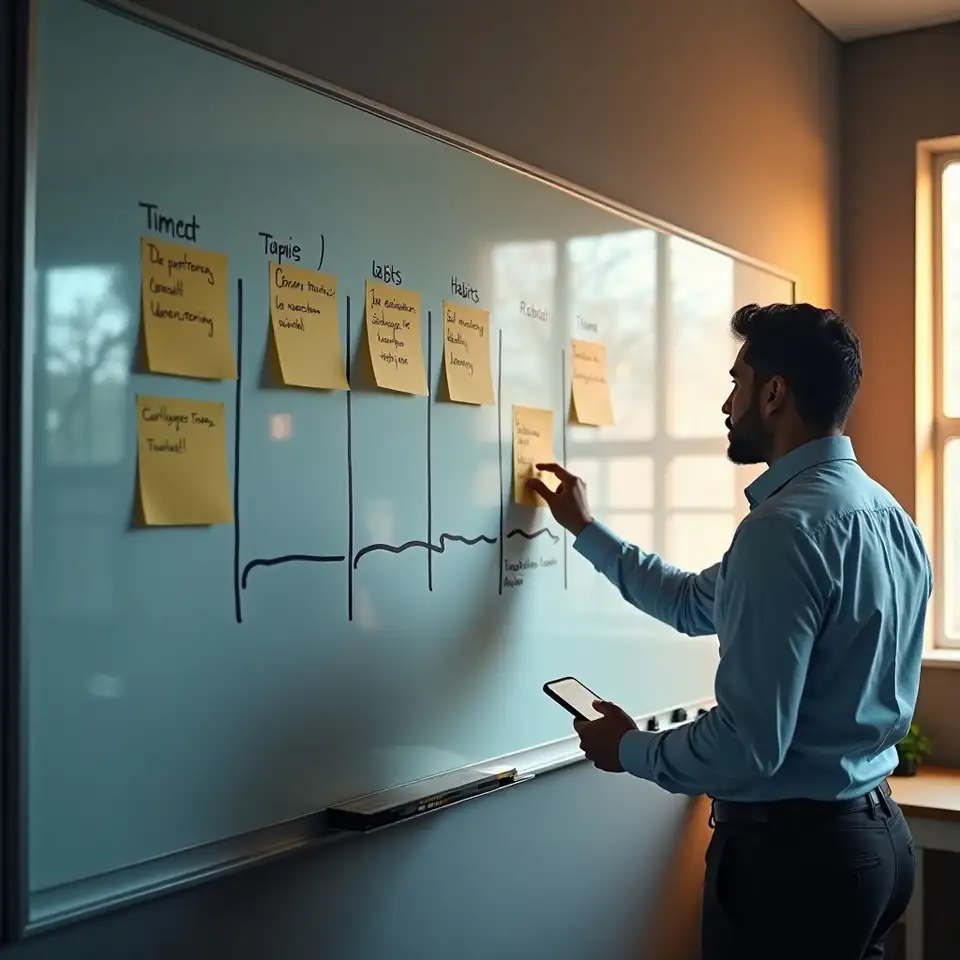
Monthly decision timeline
Map your month with this timeline worksheet that marks salary dates, regular bills, and predictable temptation points such as sales or social events. By placing these on one line, you can see where present bias tends to strike and decide where a prompt, reminder, or small rule could do the most work for your saving habits.
Quick tips for saving despite present bias
Automate early, not later
Slow down big decisions slightly
Use visible reminders of the future
Place visual cues where spending decisions happen, like a simple note near your wallet or on your phone lock screen, reminding you of one specific future goal instead of a vague idea of saving more.
Review plans against reality regularly
Schedule brief reflection sessions, weekly or monthly, to compare what you planned to save with what actually happened, then adjust your rules instead of blaming yourself for every slip.
Run experiments, not life overhauls
Behaviour terms behind our tools
Present bias
Bias
Present bias
Bias
Hyperbolic discounting
Time
Hyperbolic discounting
TimeHyperbolic discounting describes how we treat near future outcomes as much less valuable than immediate ones, while treating distant future outcomes more similarly to each other. This uneven discounting makes it easier to delay saving decisions again and again, because each short delay feels small, even though the long term impact can be large.
Loss aversion
Risk
Loss aversion
RiskLoss aversion is a pattern where the pain of losing something feels stronger than the pleasure of gaining the same amount. For saving, this can mean people avoid moving money into a separate account because they feel they are losing spending power today, even if they logically know it supports future stability.
Mental accounting
Framing
Mental accounting
Framing
Status quo bias
Bias
Status quo bias
Bias
Time inconsistent preferences
Planning
Time inconsistent preferences
PlanningTime inconsistency refers to how our preferences shift as decisions move from the future into the present. A plan made calmly at the start of the month may look less appealing when salary arrives and temptations appear. This inconsistency is closely linked to present bias and helps explain why saving plans often break down at predictable moments.
Self control conflict
Emotion
Self control conflict
EmotionSelf control conflict is the internal struggle between the part of you that wants long term stability and the part that wants immediate relief or pleasure. This conflict is common in saving decisions, especially after stressful days, and recognising it can help you design rules that protect your future self when willpower feels low.
Automaticity in saving
Habits
Automaticity in saving
HabitsAutomaticity is the process of turning repeated actions into habits that require little conscious effort. In the context of saving, setting up automatic transfers or fixed rules can harness automaticity so that present bias has fewer chances to derail decisions, though it cannot remove uncertainty or guarantee specific outcomes.
Choice architecture
Context
Choice architecture
ContextChoice architecture is the way options are presented, including defaults, ordering, and prompts. Small design choices, such as making saving the default or showing a simple comparison table first, can nudge people toward more future friendly decisions without removing freedom, which is important when present bias is strong.
Implementation intentions
Planning
Implementation intentions
PlanningImplementation intentions are specific if then plans that link a situation to an action, such as deciding in advance what you will do on salary day. They work by reducing the mental effort needed in the moment, which can help counter present bias when you face the usual temptations or pressures around saving.
Using these resources
How often should I use these tools
Most tools are designed for weekly or monthly use. Our team suggests you start with one checklist or table for a full month, then review what actually changed before adding anything new. Results may vary and habits take time.
Can I customise the worksheets
Yes, you can adapt numbers, categories, and wording to match your income, culture, and family setup. The key is to keep the structure simple so present bias stays visible instead of hiding behind complex details.
Should I use these with an adviser
You can use them alone, with a partner, or together with a trusted financial professional. We recommend sharing your filled tables or notes with advisers so they understand your behavioural patterns, not just your numbers.
What if a tool does not work for me
If a tool feels heavy, skip it for now and try something lighter. Our methodology is based on small experiments, so it is normal to drop or adjust tools that do not fit your life. Behaviour change is gradual and results may vary.